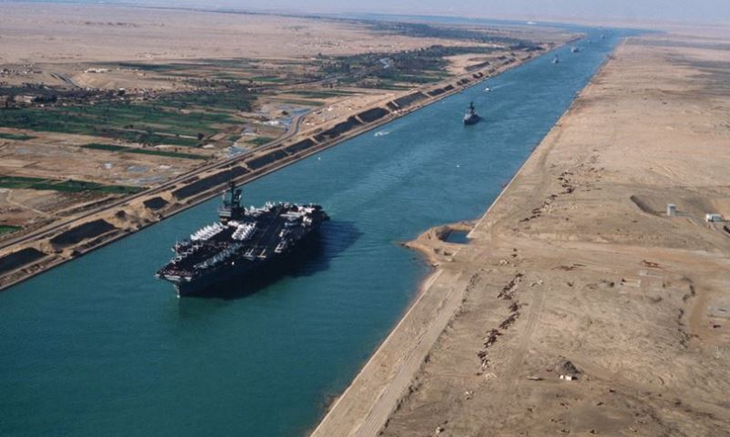
Suez Canal Container Ship Transits Exceed 50% of Pre-Disruption Levels
Container ship
transits through the Suez Canal have exceeded 50% of pre-disruption levels for
the first time since Houthi attacks began in the Red Sea, signalling a gradual
return to normal shipping routes, according to BIMCO. During the first two weeks of October 2026,
weekly container ship capacity transiting the canal averaged 753,000 TEU,
compared with 1.457 million TEU during the corresponding period in 2023,
according to Clarksons Research.
“Since the Houthi attacks began in the Red Sea, this is the first time
that transits have exceeded 50% of pre-disruption levels,” said Niels
Rasmussen, Chief Shipping Analyst at BIMCO.
The disruption began in November 2023, when the Houthis announced plans
to target Israeli ships in the Red Sea in response to Israeli attacks in Gaza.
The criteria were subsequently broadened to include other vessels, creating
uncertainty across global shipping markets.
In response, container shipping lines began diverting vessels away from
the Suez Canal and the Red Sea in December 2023, opting instead to sail around
the Cape of Good Hope. By the final week of 2023, weekly container ship
capacity transiting the canal had plunged to 330,000 TEU, against a
year-to-date weekly average of 1.29 million TEU. Between early February 2024 and mid-2026,
weekly container ship capacity through the Suez Canal averaged just 141,000
TEU, equivalent to approximately 11% of the capacity recorded during the
corresponding weeks of 2023. The
recovery has gathered momentum since the Gemini Alliance, comprising Maersk and
Hapag-Lloyd, announced on 6 July 2026 that its AE15/SE3 Asia–Mediterranean
service would return to the Suez Canal.
The alliance has since announced the return of five additional services
to their normal routes, including its remaining three Asia–Mediterranean
services. Members of the Ocean Alliance and Premier Alliance, along with MSC,
have also announced routing changes.
In total, changes involving 16 services have been announced since early
July, reflecting growing confidence in the resumption of Suez Canal
transits. During the first two weeks
of October, 36% of total container ship capacity routed through either the Suez
Canal or the Cape of Good Hope passed through the canal. This compares with an
average of just 8% between 2024 and mid-2026.
However, the figure remains well below the 80% share recorded before the
attacks began, indicating that a full return to pre-disruption routing patterns
is still some distance away. The
initial recovery in Suez Canal traffic was driven largely by southbound
sailings. During the third quarter of 2026, northbound capacity through the
canal stood at just 75% of southbound capacity. This ratio increased to 81%
during the first weeks of October, indicating a gradual improvement in traffic
flows in both directions. The shift
back to the shorter Suez Canal route is also expected to reduce the additional
vessel capacity absorbed by longer voyages around Africa. BIMCO estimates that rerouting away from
the Suez Canal increased global container ship demand by approximately 10%, as
vessels spent more time completing voyages via the Cape of Good Hope. “That increase is now reducing quickly.
However, as the return to the Suez Canal has coincided with increased port
congestion in Asia, the full effect on supply/demand has yet to be seen,”
Rasmussen said.
The accelerating
return to Suez Canal routes could release effective shipping capacity and
influence freight market conditions. However, the extent of any impact on
global container shipping supply and demand will depend on the pace of route
normalisation and the continuing effects of congestion at Asian ports.
Related News