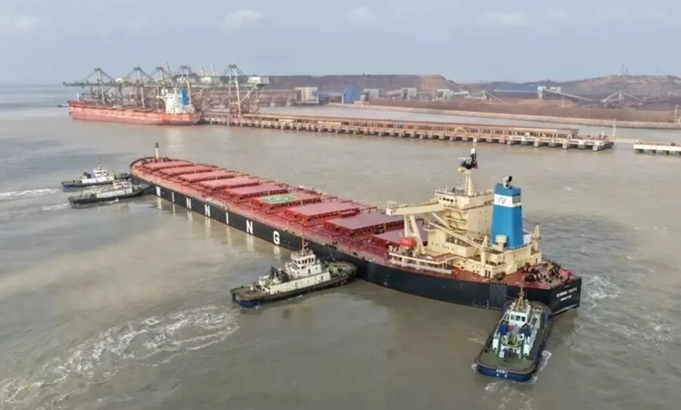
Global shipyard order book grows 13%, strengthening China’s lead
“On 1 September 2026, the global shipyard order book
reached an estimated 203.2m Compensated Gross Tonnage (CGT), up 13% from 180.0m
CGT a year earlier,” says Niels Rasmussen, Chief Shipping Analyst at BIMCO. This is slightly below the all-time high of 210.4m CGT
reached in May but remains above the previous record of 195.4m CGT from 2008. Much of the growth has been captured by
Chinese shipyards, who secured 74% of the CGT contracted during the past year.
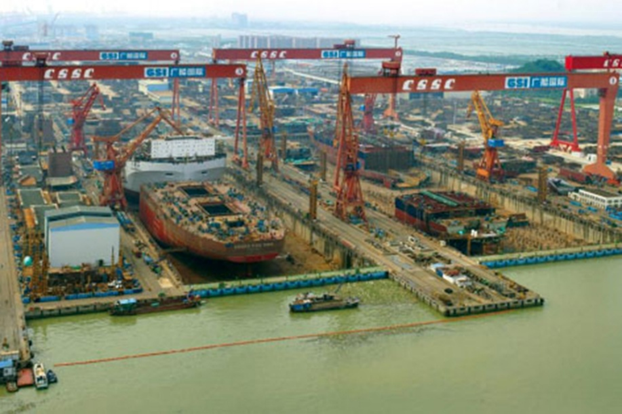
This has further strengthened China’s position as the world’s largest
shipbuilding nation. Chinese shipyards now hold 64% of the global order book
while South Korean shipyards hold 19% and Japanese 6%. China’s dominance extends across the major
cargo-carrying ship sectors. Its shipyards hold more than 72% of the order book
in each of the six main sectors: container, tanker, gas tanker, dry bulk, other
dry cargo and RoRo. Combined, these sectors account for 88% of the global order
book. Their yards’ largest share is in the container ship segment, with 81% of
the order book. “Container ships
dominate both the order book and its growth over the past 12 months. They
account for 30% of CGT on order and 68% of the increase during the past year,”
says Rasmussen. Additionally, Chinese
shipyards currently have better capacity coverage than their South Korean and
Japanese competitors. If each shipyard’s current capacity is assumed to equal
its highest annual CGT output during 2021–2025, Chinese shipyards hold orders
equivalent to an average of 4.2 years of capacity. The corresponding figures
for South Korean and Japanese yards are 1.9 and 1.7 years. Combined deliveries from China, South
Korea and Japan peaked at 40.1m CGT in 2025, but 55.9m CGT and 60.0m CGT are
currently scheduled for delivery in 2027 and 2028. Chinese yards, in
particular, will have to raise output to manage the scheduled deliveries. Current capacity could therefore be
assumed to equal the highest annual CGT delivered or scheduled for delivery
during 2021–2030. In that case, average coverage falls to 2.1 years for Chinese
shipyards and 1.6 years for both South Korean and Japanese shipyards.
“China has further strengthened
its position as the world’s leading shipbuilding nation, but its shipyards must
raise annual output to new record highs in order to deliver. Chinese yards are
scheduled to deliver a record 44.0m CGT in 2028, nearly twice the 22.7m CGT
delivered in 2025. The capacity expansion needed to achieve this could increase
the risk of underutilisation if contracting weakens in the future,” says
Rasmussen.
Related News