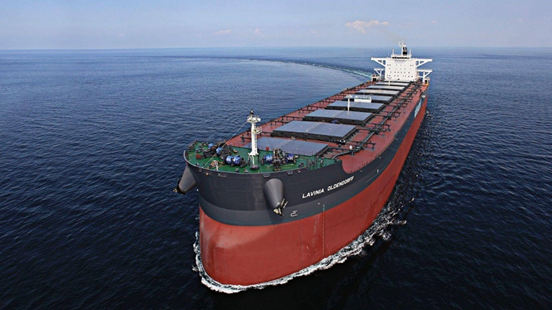
Dry Bulk Shipping: Escalating attacks on ships heighten uncertainty
Typically,
around 4% of dry bulk demand sails via the Strait of Hormuz. Alternative routes
have softened the impact of the disruption but have been unable to replace
pre-war volumes. The disruption has also tightened energy and fertiliser
supplies, weighing on global economic growth and raising concerns over food
security.Given the uncertainty, BIMCO presents two forecast scenarios. The “SoH
closed” scenario assumes that the strait remains effectively closed throughout
2027 and 2028, while the “SoH open” scenario assumes that ships can freely
transit the strait from 2027 onwards. “We
expect the dry bulk supply/demand balance to gradually weaken in 2027 and 2028,
although from a high baseline. Cargo volume growth is expected to be limited,
while ship deliveries accelerate, particularly in the capesize segment,” says
Gouveia. In 2027, ship demand is
forecast to grow 0.5-2.5% if the Strait of Hormuz remains effectively closed,
compared with supply growth of 3-4%. If the strait reopens, both demand and
supply growth are expected to be 1 percentage point higher. In this scenario,
demand would grow faster for commodities other than coal supported by improved
economic conditions and stronger import demand from countries in the Persian
Gulf. However, the fleet currently trapped in the Gulf would begin operating as
normal and sailing speeds could remain slightly higher than in our other
scenario, increasing supply. In 2028,
ship demand is forecast to grow 0.5-2.5% in both scenarios, while supply is
expected to grow 3-4%. Cargo volume growth is expected to remain limited as
coal shipments decline, while the return of bulkers to the Panama Canal could
weigh on average sailing distance growth. On the supply side, rising ship
deliveries are expected to support strong fleet growth, even as ship recycling
increases. Lastly, average sailing speeds are expected to decrease slightly as
market conditions soften.
“Disruptions
to Black Sea shipping pose an additional downside risk to the market outlook.
The forecast assumes that Russian and Ukrainian grain volumes unable to be
shipped in 2026 are instead exported in 2027. If they remain unavailable, dry
bulk cargo growth could be up to 0.5 percentage points weaker in 2027 and grain
shipment growth up to 4 percentage points weaker,” says Gouveia.
Related News