Crude Tanker Rates Reach Record Levels; hit all-time highs on Friday 12th September
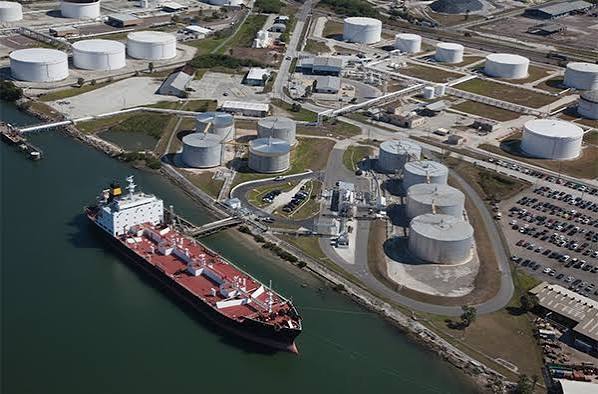
The crude tanker market is again at extraordinary rate levels. The combination of both “enough” volume (Mid. East crude flows are “only” 4.5m bpd down) and major inefficiencies as the tanker market provides the logistical flexibility needed has developed. With voyages lengthening further (e.g. ~50% of Red Sea oil now heading to Asia via the SUMED pipeline (or Suez) and then the Cape of Good Hope to bypass the Houthi threat) and inefficiencies related to STS transfers building (e.g. ~15% of the VLCC fleet is now off Oman, start-July: 10%), global VLCC earnings rose by 68% to a fresh high of $451,000/day amid records in the West (USG-China freight: $37.5m, $19/bbl) and East (Oman–Korea: $572,000/day).
Gains have filtered down through the sizes, with global Suezmax earnings up 94% w-o-w to a record $343,000/day. Across other energy shipping segments, VLGC rates remain elevated at $163,000/day amid continued disruption at Panama (5% of VLGC fleet waiting to transit Panama earlier this week, 2% in August), but LNG carrier spot rates are now soft ($27,000/day) with more US LNG being shipped shorter-haul to Europe (stocks are at a >10-yr seasonal low).
Despite major disruption, energy markets, supported by the logistical flexibility shipping markets provide, continue to show resilience in getting oil “to market”.
Related News